Quantitative research on hedge fund positioning and flows
The research of Sophos Alpha, an independent quantitative research desk: the daily desk notes and the weekly Institutional Monitor, on hedge fund and systematic positioning, dealer gamma, volatility and the cross-asset flows they drive.
Latest research
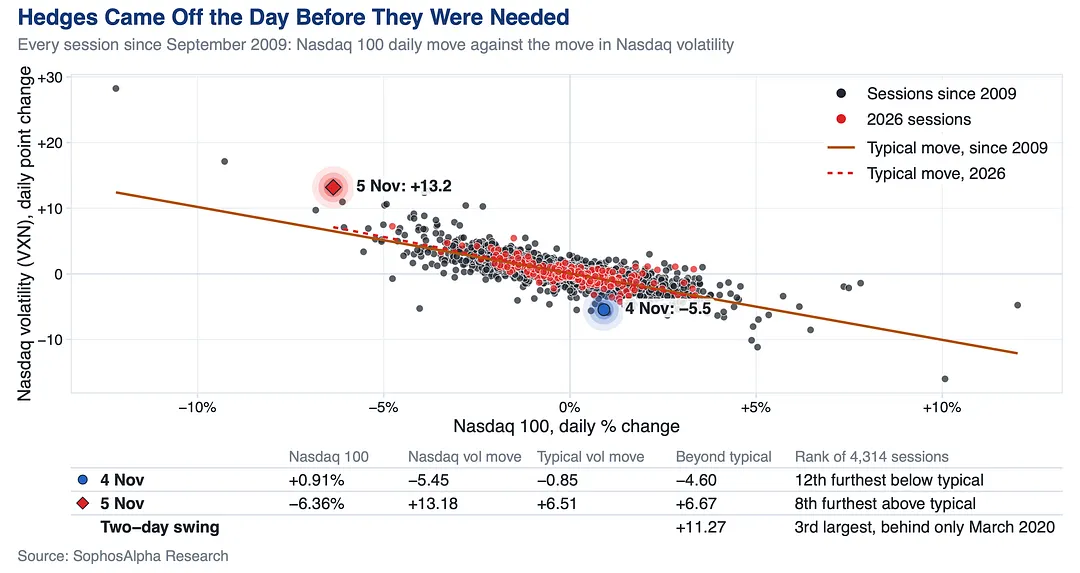
Caught Unhedged: The Mechanics of a Forced Selloff
How systematic funds were forced to unwind last week, why a market that had just shed its hedges could not absorb it, and what it cost the hedge funds caught on the other side.
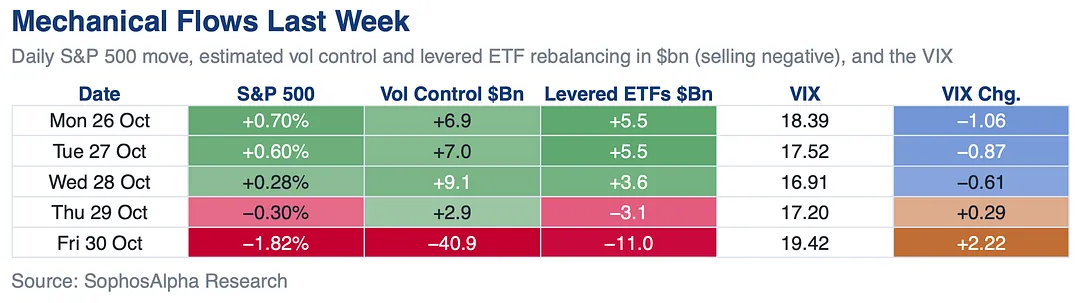
- Selling creates volatility. Volatility creates more selling.Institutional Monitor
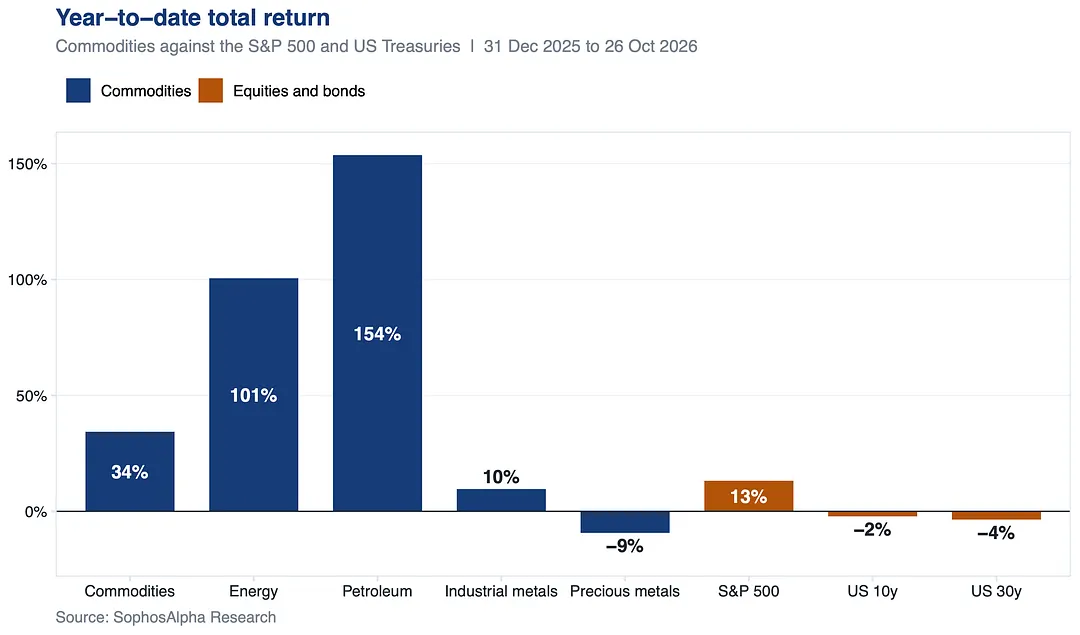
- Commodities did the hedging this yearInstitutional Monitor
- Asset managers got caught in a record VIX shortInstitutional Monitor
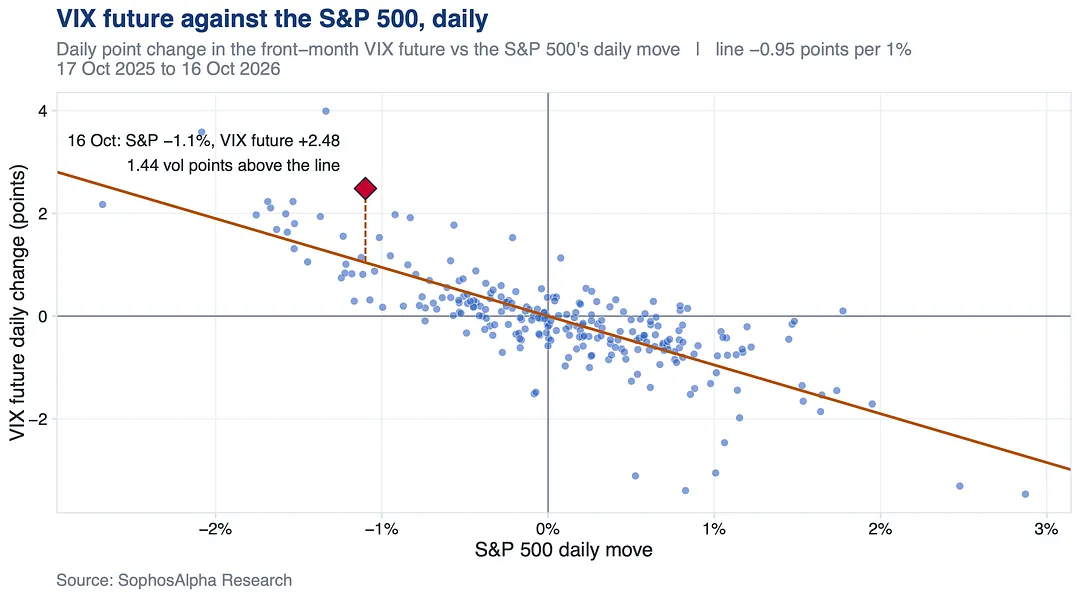
- Bond positioning has split in twoInstitutional Monitor
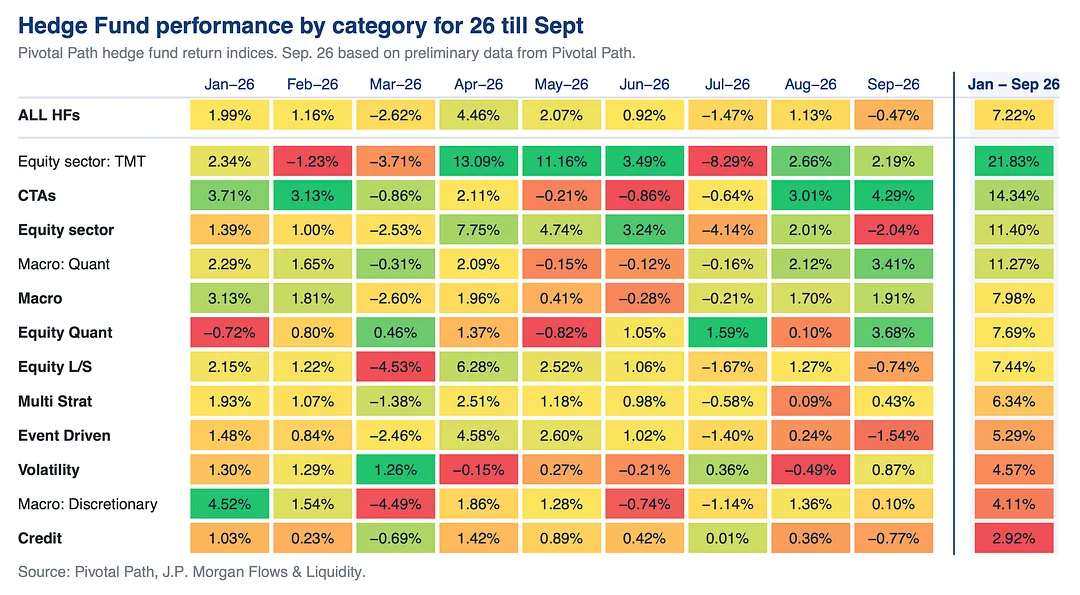
- Where rates start to hurt equitiesInstitutional Monitor
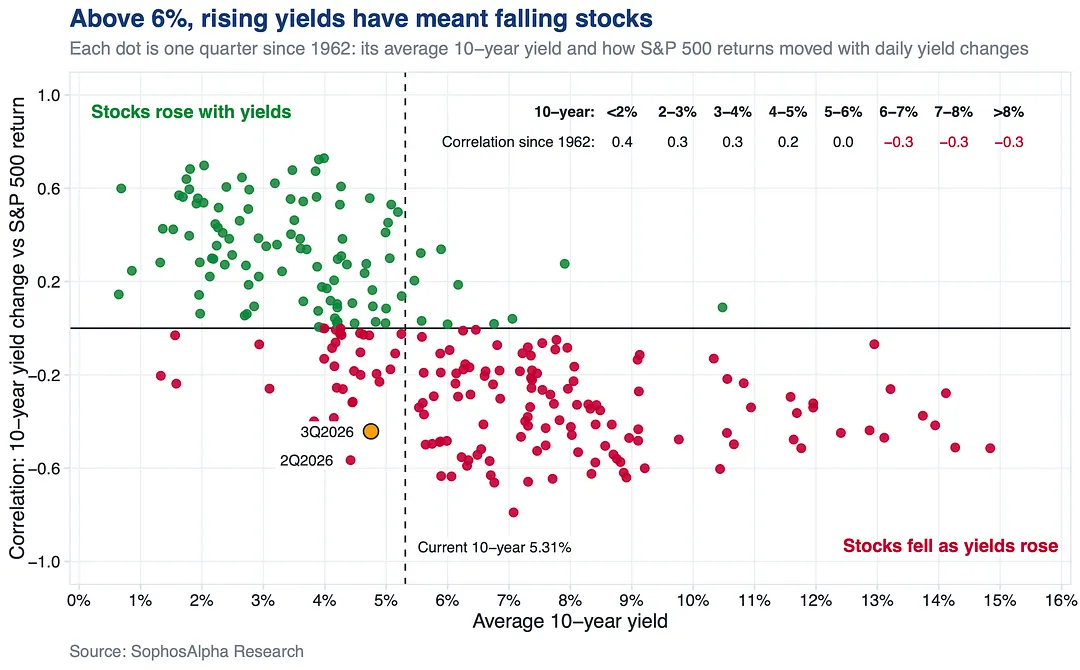
- An index book without Energy is short oilInstitutional Monitor
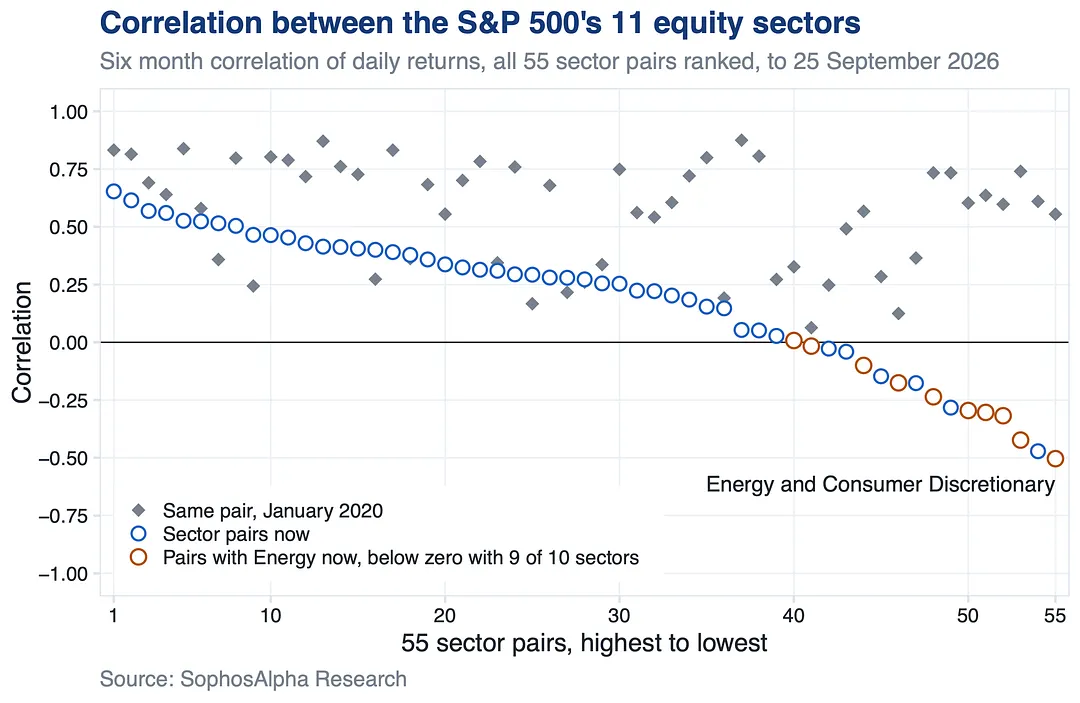
Desk notes
One chart, one observation.
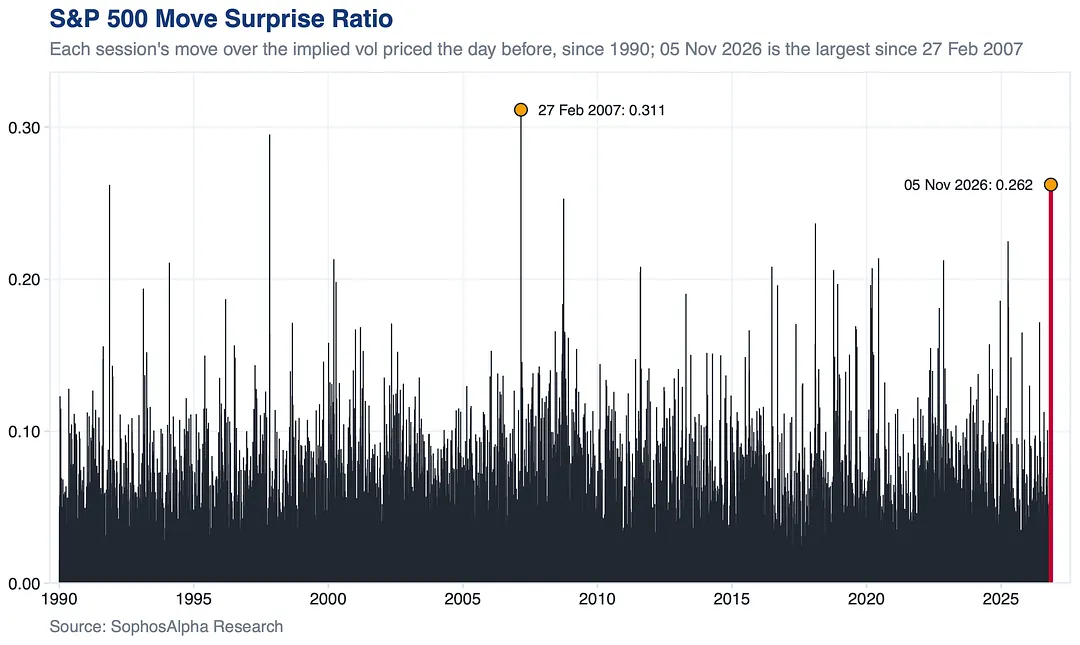
- The options market priced about a 1% day for the S&P 500 last Thursday.
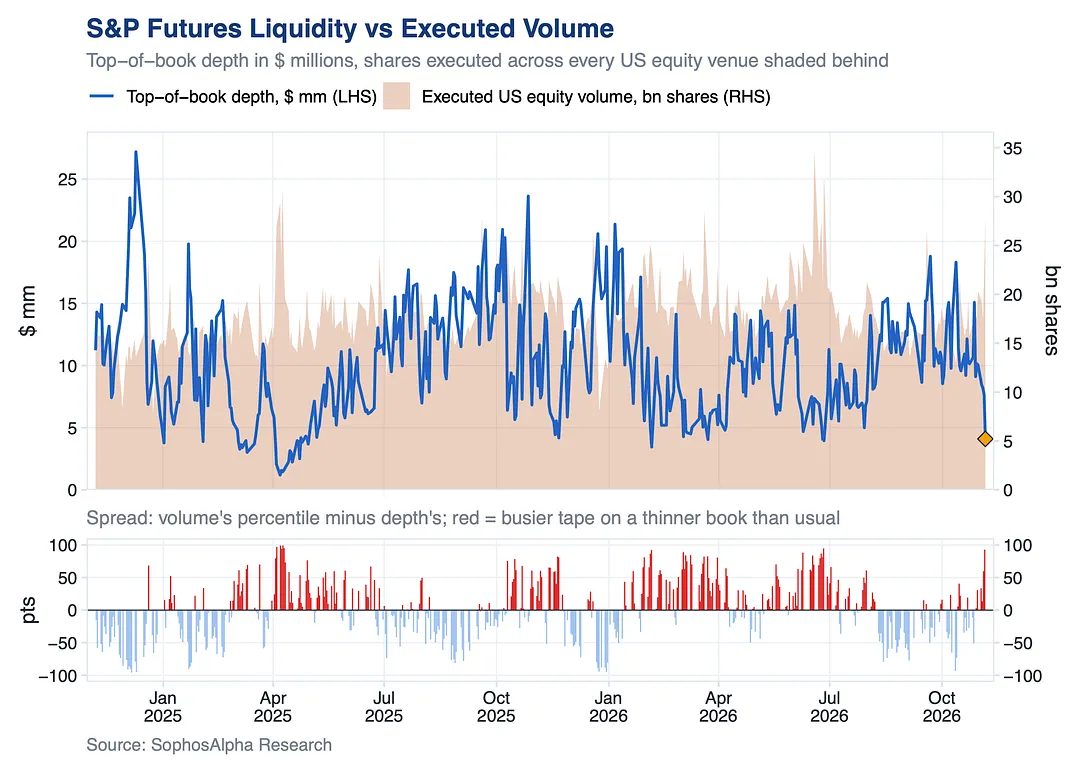
- Just when the market needed it most, liquidity at the top of the book evaporated.
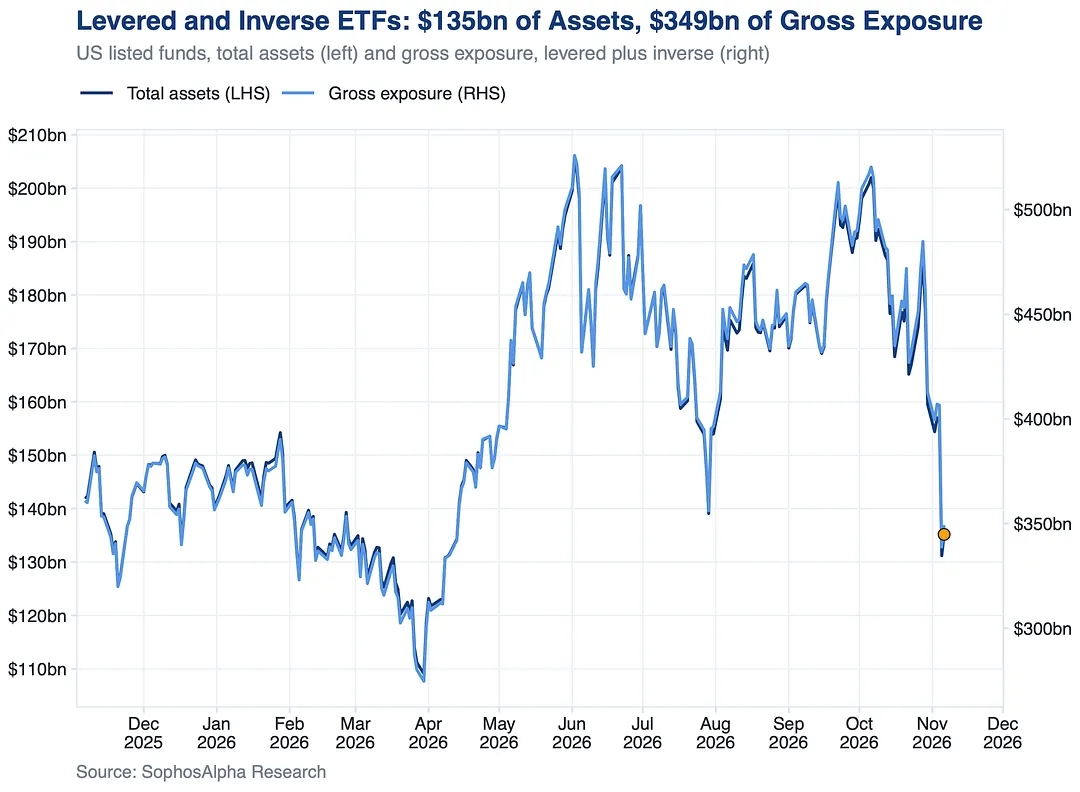
- A third of the leverage in US levered ETFs is gone in five weeks.
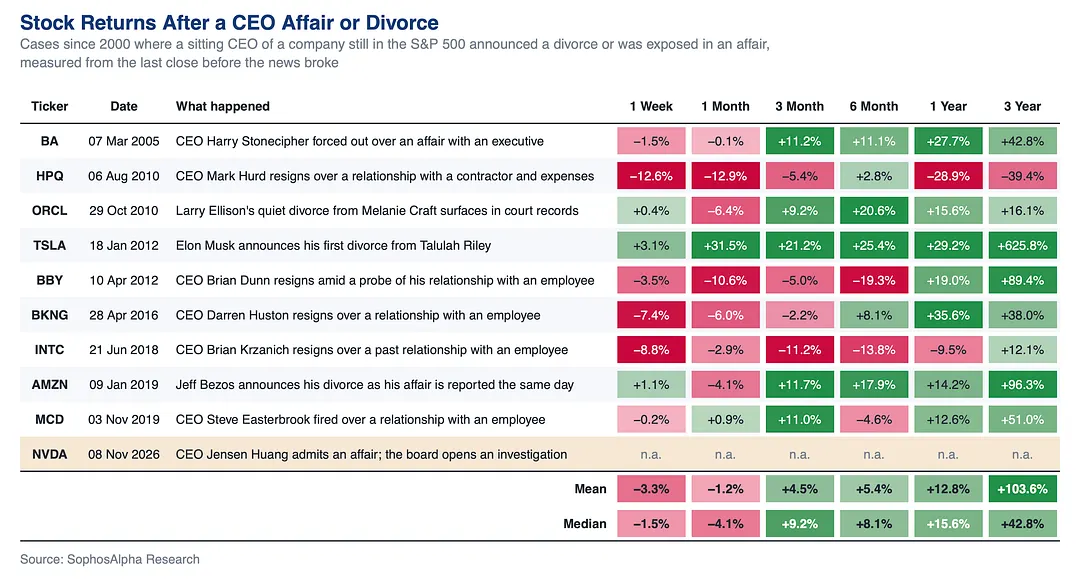
- CEO scandals hurt the stock for about a month.
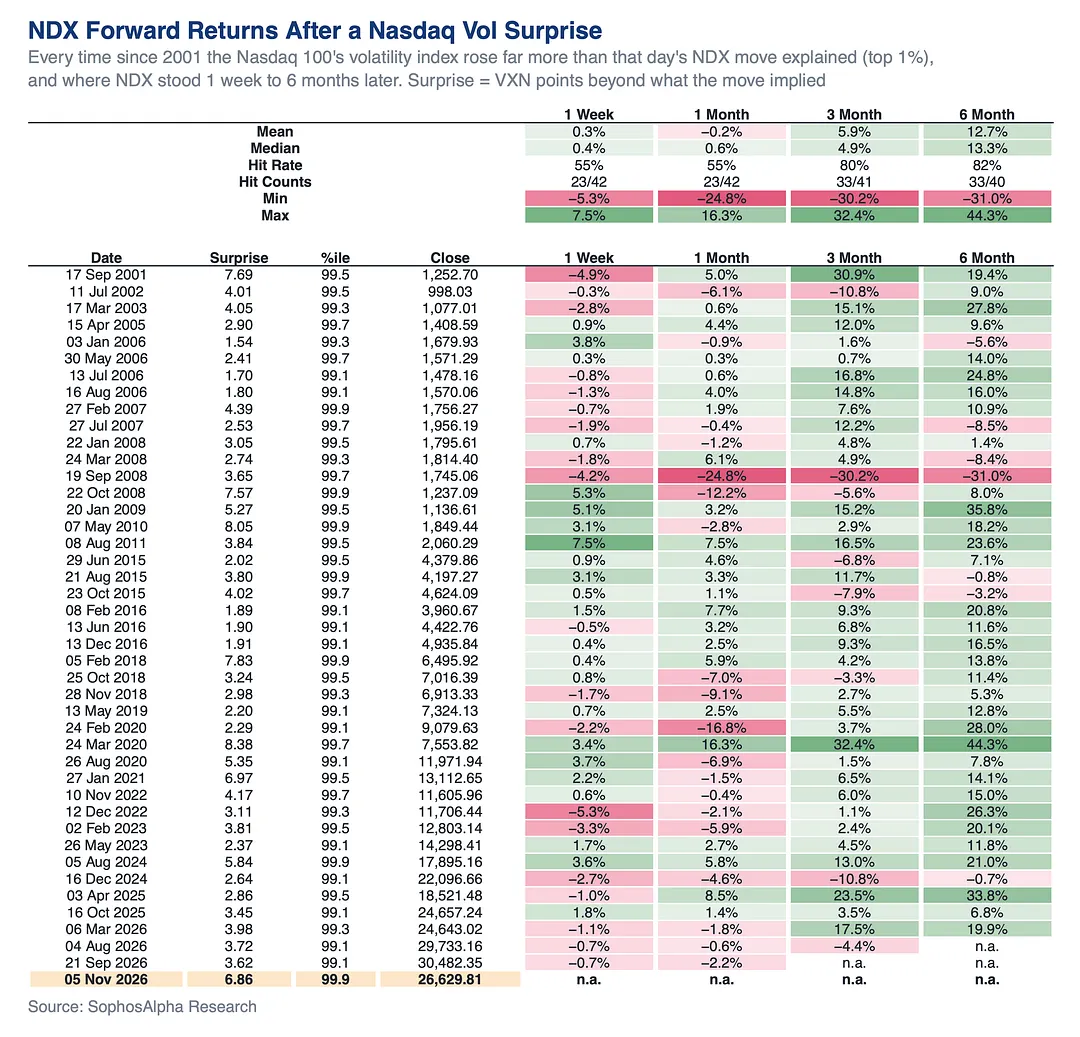
- After a volatility shock like last Thursday's, the Nasdaq 100 has tended to chop for a month before it recovers.
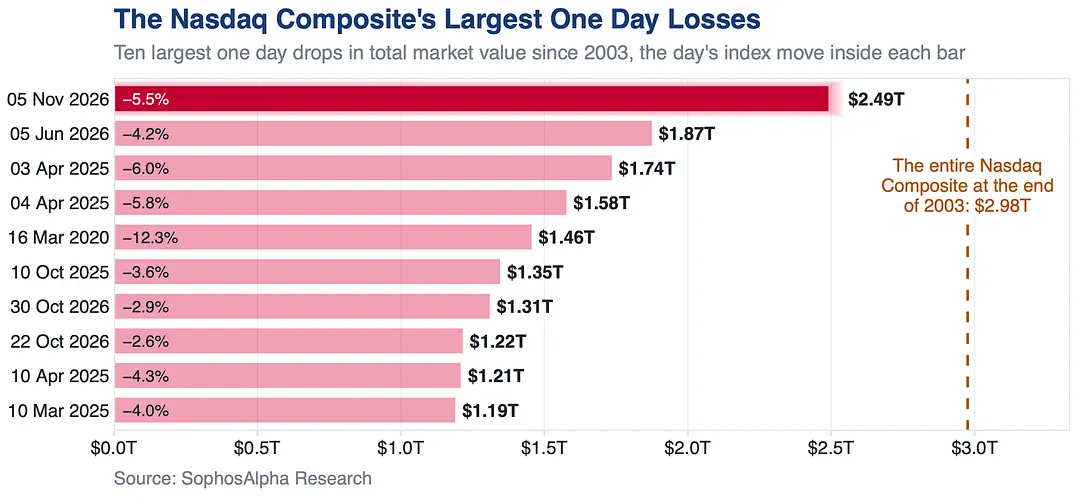
- The Nasdaq lost $2.49 trillion in market value last Thursday.